Foreign Heirs of US Estates
An inheritance from the United States reaches an heir abroad only after the estate has cleared the federal estate tax, secured the release of the assets and withheld what the Code requires on income paid across the border. The firm administers and advises such estates and trusts, settles the withholding and the treaty position before each payment, and works with the heir’s advisors in the country of residence.
Law stated as of October 2026
In brief.
- The heir’s status, not the address, selects the rules: a US citizen or green card holder living abroad is not a nonresident alien, and the withholding of section 1441 reaches only the nonresident alien heir (sections 1441(a) and 7701(b)(1)).
- An estate or trust withholds 30 percent of the US-source fixed or determinable income it distributes to a nonresident alien beneficiary; an estate withholds on the distributable net income actually distributed (section 1441(a); Treas. Reg. § 1.1441-5(b)(2)(iii)).
- A treaty rate applies only if the fiduciary holds a beneficial owner certificate, for an individual the Form W-8BEN, before the payment; a fiduciary that fails to withhold is liable for the tax (Treas. Reg. § 1.1441-6(b)(1); section 1461).
- For a decedent who was neither a US citizen nor domiciled in the United States, a return is required once the US-situs gross estate exceeds USD 60,000, less certain lifetime gifts; the tax is a lien on the gross estate for ten years (sections 6018(a)(2), (3) and 6324(a)(1)).
- A US custodian avoids liability for that tax only by obtaining an IRS transfer certificate before release, unless no return is required or an executor appointed and acting in the United States administers the assets; without one, whoever holds the property is the executor (Treas. Reg. § 20.6325-1; section 2203).
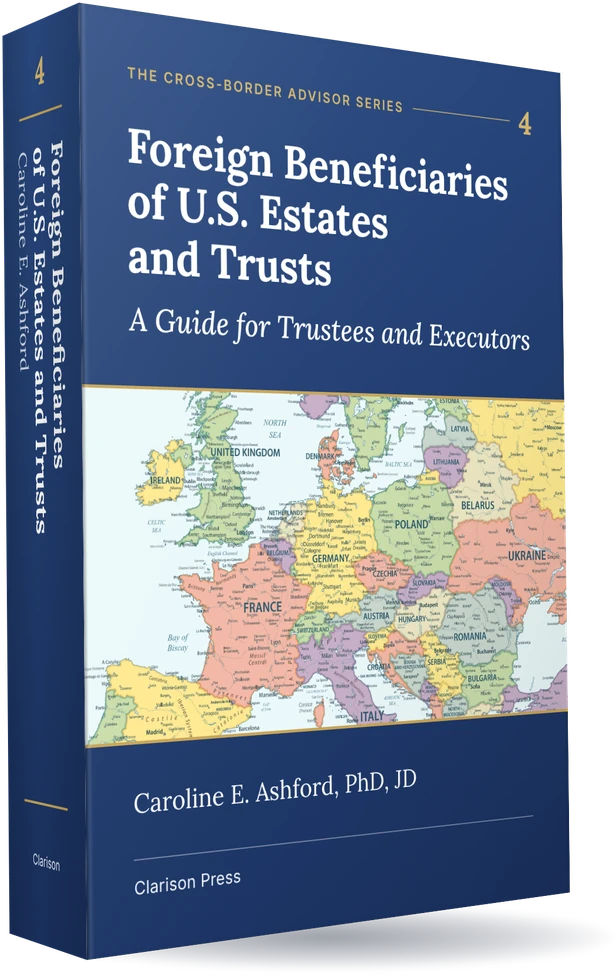
A Guide for Trustees and Executors. About 470 pages. In preparation; USD 200.
Publication noticeHeirs in Germany are served in German on Vermoegen-USA.com, heirs in France in French on Patrimoine-americain.com.
On the French side of a succession, French notaries and advisors from the firm’s network advise.
Situations for heirs abroad and the fiduciaries who pay them
Each page sets out what is happening, what has to happen and in what order, how the firm helps, and what documents to prepare for the initial consultation.
Someone living abroad has died, leaving assets in the United States
The firm files Form 706-NA, requests the transfer certificate and has the US assets released to the persons entitled to them.
Situation →
An estate in Washington DC, Maryland, Virginia or California has heirs abroad
The firm takes the estate through probate and the accounting to the final distribution, with the withholding settled before each heir abroad is paid.
Situation →
An estate or trust is paying a beneficiary abroad
The firm settles the withholding rate and the treaty claim and has the forms in the file before the money leaves the account.
Situation →
Selling US real estate owned from abroad
The firm deals with the FIRPTA withholding and the withholding certificate and advises the estate or the heirs through the closing.
Situation →What an inheritance from the United States involves
Beneficiaries outside the United States
The heir’s status, the estate’s income tax return and Schedule K-1, the withholding on each distribution and the treaty claim, set out for the beneficiary abroad.
Release of a nonresident’s US assets
When a US custodian may hand over the assets of a decedent who lived abroad: the USD 60,000 threshold, the statement of facts and the certificate itself.
Withholding on distributions abroad
Which part of a distribution carries out US-source income, the 30 percent and treaty rates, the Form 1042 series and the fiduciary’s own liability for what was not withheld.
Taxpayer identification numbers
When a beneficiary abroad needs a US taxpayer identification number, how an ITIN is obtained, and the circumstances in which backup withholding applies to a distribution.

Ancillary probate
Which US assets of a decedent who lived abroad require a court proceeding in the state where they are located, and who may be appointed there.
The executor’s order of steps
A guide for the personal representative of an estate with assets or heirs in more than one country, from the first weeks after the death to the final distribution.
Material for foreign heirs of US estates
Describe the estate
Where the decedent lived, what the estate or trust holds and in which states, and where each heir lives and which citizenships each holds. The firm then sets out what it needs and the order in which it would proceed.